Venture Global (NASDAQ:VG), a prominent U.S.-based exporter of liquefied natural gas (LNG), is set to release its financial results for the third quarter of 2026 on November 10, prior to the market opening. This announcement will provide insights into the company’s performance during this period, offering a detailed look at how various factors have influenced its operations.
In the previous quarter, Venture Global reported earnings of $0.51 per share, which exceeded the Zacks Consensus Estimate of $0.49. This marked the third instance in the last four quarters where the company surpassed expectations, achieving an average earnings surprise of 10.03% over this period. Such performance is indicative of the company’s ability to navigate market conditions effectively.
For the upcoming third quarter, the Zacks Consensus Estimate for earnings per share (EPS) is set at $0.50. This estimate has experienced one upward revision and four downward revisions over the past 30 days. The projected EPS signifies a substantial improvement of 212.5% when compared to the same quarter last year. Additionally, the revenue forecast for the third quarter stands at $4.6 billion, reflecting a 39.4% increase from the previous year. These figures highlight the company’s growth trajectory and its ability to capitalize on market opportunities.
Key Factors Influencing Venture Global’s Performance
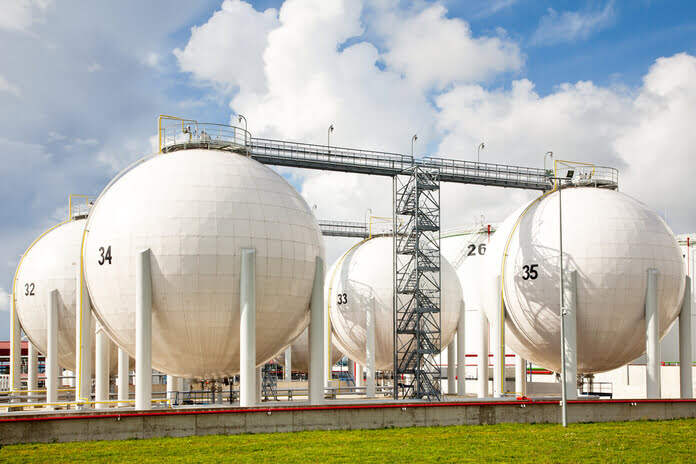
Venture Global is recognized as one of the largest exporters of LNG in the United States. The company’s performance in the third quarter is expected to have been bolstered by rising international demand for LNG, particularly from markets in Asia and Europe. This demand surge can be attributed to the global shift towards cleaner energy sources, with LNG playing a crucial role in energy transition strategies worldwide.
The company’s business model relies on a mix of long-term and medium-term contracts, which provide stability against fluctuations in the spot LNG market. These contracts help secure consistent earnings and cash flows, while the medium-term agreements allow the company to capitalize on higher prices when market conditions are favorable. This strategic approach ensures that Venture Global can maintain a steady revenue stream even amid volatile market conditions.
According to a recent 8-K filing, Venture Global reported the sale of 124 LNG cargoes in the third quarter, surpassing the number sold during the same period in 2025. This increase in sales is anticipated to have positively impacted the company’s earnings for the quarter. The ability to increase sales volume reflects the company’s operational efficiency and its capacity to meet growing demand.
Despite these positive factors, Venture Global may have faced challenges in the third quarter, particularly related to feed gas costs, which could have risen due to regional demand dynamics. Additionally, inflationary pressures may have led to higher operating expenses, potentially affecting the company’s financial performance during this period. These challenges underscore the complexities of operating in the energy sector, where costs can be influenced by a myriad of external factors.
Analyst Expectations and Comparisons
Currently, Venture Global holds a Zacks Rank #2, indicating a ‘Buy’ rating. However, the company’s Earnings ESP (Expected Surprise Prediction) is -2.18%, suggesting that an earnings beat may not be likely this time around. The Earnings ESP is a critical metric used by analysts to gauge the likelihood of a company surpassing earnings expectations, and a negative value indicates potential challenges ahead.
In comparison, other energy sector companies such as PBF Energy (NYSE:PBF), HF Sinclair Corporation (NYSE:DINO), and Galp Energia SGPS SA (OTC:GLPEY) hold a Zacks Rank #1, indicating a ‘Strong Buy’ rating. PBF Energy, for instance, operates a geographically diverse refining network with a significant processing capacity, which supports higher margins. Its operations include six refineries with a combined throughput capacity of 1 million barrels per day, enabling it to process a wide range of feedstocks.
HF Sinclair has a robust network of seven complex refineries across various regions, including the Mid-Continent, Southwest, Rocky Mountains, and Pacific Northwest. The outlook for the company’s refining business remains constructive due to tightening supplies of refined products and a supportive crack environment. This positioning allows HF Sinclair to benefit from favorable market conditions and maintain a competitive edge.
Galp Energia, a Portuguese energy company, has made promising discoveries in oil exploration, particularly in the Orange Basin offshore Namibia. This discovery allows Galp to diversify its global presence with the potential to become a significant oil producer in the region. The company’s ability to refine and market oil products and gas, as well as engage in marketing and sales activities, further strengthens its market position.
These companies, with their diverse operations and strategic positioning, provide interesting comparisons to Venture Global’s performance and outlook in the energy sector. The energy landscape is highly competitive, and each company’s unique strengths contribute to its ability to navigate market challenges and capitalize on opportunities.
Footnotes:
- Venture Global’s expected earnings per share for Q3 2026 is $0.50, with a projected revenue of $4.6 billion. Source.
- Venture Global sold 124 LNG cargoes in Q3 2026, an increase from the previous year. Source.
- Venture Global’s Zacks Rank is #2, with an Earnings ESP of -2.18%. Source.
Featured Image: Depositphotos @ Arcady